
Types of Special Needs Trusts in Florida: A 2026 Family Guide
- Kelly Mata
- Aug 21
- 12 min read

Updated: Aug 23
A single inheritance or a well-meaning gift could unintentionally strip your loved one of their essential Medicaid and SSI benefits overnight. For many Florida families, the $2,000 asset limit for Supplemental Security Income feels like a legal trap that prevents long-term security. Understanding the various types of special needs trusts in Florida is the key to escaping this dilemma. You've worked hard to build a legacy, and it's frustrating to feel like the system punishes your family for trying to plan ahead. You deserve a strategy that adapts to your unique situation rather than a rigid, outdated approach.
This guide helps you discover the specific legal structures available to protect your loved one’s government benefits while securing their financial future. By exploring these options, you can create a clear financial roadmap that ensures your family member is cared for long after you are gone. We will explore the critical differences between first-party, third-party, and pooled trusts; we'll also examine how 2026 updates like the ABLE Age Adjustment Act provide new opportunities for independence. You'll move from confusion over complex terminology to the peace of mind that comes from a streamlined, professional legal structure.
Table of Contents
Understanding Special Needs Trusts (SNT) in Florida
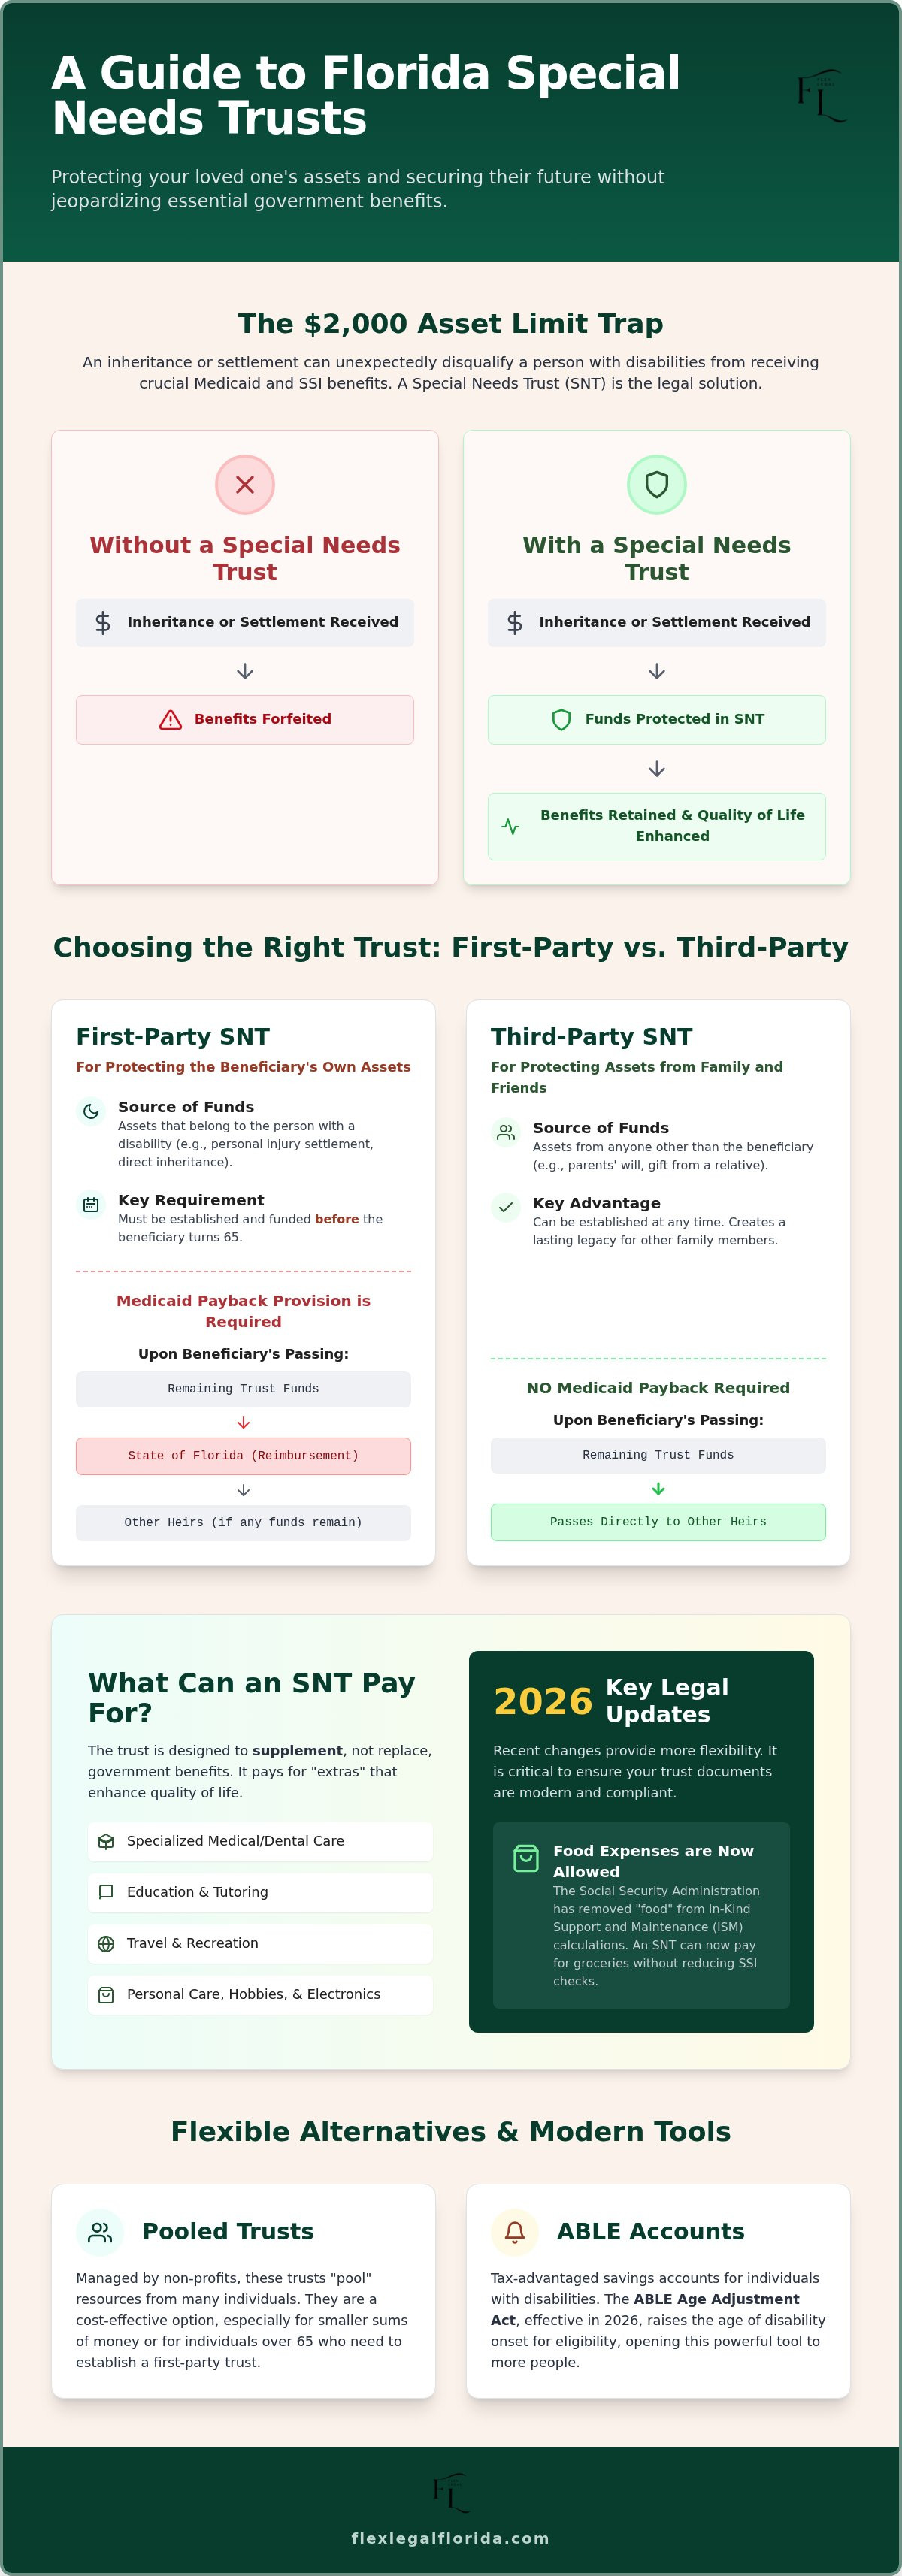
A Supplemental Needs Trust (SNT) is a specialized legal arrangement that allows a person with disabilities to benefit from financial assets while remaining eligible for means-tested government programs. In Florida, maintaining this eligibility is a delicate balancing act. For 2026, the monthly income cap for an individual to qualify for Medicaid long-term care is $2,982. Meanwhile, the asset limit for Supplemental Security Income (SSI) stays at a strict $2,000. Without one of the specific types of special needs trusts in Florida, any inheritance or settlement exceeding these limits could trigger an immediate loss of essential healthcare and income support.
The core purpose of these trusts isn't to replace public assistance. Instead, they supplement it. The Social Security Administration (SSA) and Florida Medicaid exercise strict oversight to ensure these funds aren't used for items already covered by government benefits. By following these rules, families can provide for their loved ones' comfort without jeopardizing the foundational support the state provides.
The Supplemental vs. Essential Needs Debate
2026 Legislative Update: ISM and Florida SB 262
Recent shifts in federal and state law have made 2026 a pivotal year for trust administration. A major change from the Social Security Administration recently removed "food" from the In-Kind Support and Maintenance (ISM) calculations. This means a trust can now pay for a beneficiary’s groceries or restaurant meals without reducing their monthly SSI check. It's a significant win for family flexibility and beneficiary independence.
On the state level, Florida SB 262 has introduced new layers of clarity regarding trust administration and the rights of beneficiaries. Because the legal landscape has shifted so rapidly, many older trusts are now outdated. They may contain restrictive language that prevents you from taking advantage of these new, more lenient food and housing rules. If your documents haven't been reviewed recently, you likely need a modernization audit with a special needs planning attorney. Updating your plan ensures you aren't leaving valuable benefits on the table due to obsolete trust language.
First-Party Special Needs Trusts: Protecting Personal Assets
A first-party special needs trust is often referred to as a self-settled or (d)(4)(a) trust. It's designed for situations where the person with a disability owns the assets directly. This might happen after receiving back-pay from SSI, inheriting money directly, or following a personal injury settlement—such as those handled by Daniella Levi & Associates, P.C.—where the resulting funds must be carefully managed to maintain eligibility. Among the different types of special needs trusts in Florida, this version has the strictest federal requirements because the money technically belonged to the beneficiary first.
Imagine a West Palm Beach resident who wins a legal settlement after an accident. If that money goes into a standard bank account, they'll lose their SSI and Medicaid coverage immediately because they've exceeded the $2,000 asset limit. A first-party SNT allows them to keep that money for specialized care while maintaining their benefits. The same applies to an unexpected inheritance that wasn't directed into a third-party trust. To comply with the Florida Statutes on trusts, the money must be used "solely for the benefit" of the disabled individual. This means funds can't be spent on other family members or shared household expenses that don't directly benefit the person with the disability.
The Role of the Trustee in First-Party Trusts
Managing a first-party trust is a complex, high-stakes job. The trustee has a fiduciary duty to handle Medicaid liens and keep meticulous records for potential Florida Medicaid audits. Because the state is a remainder beneficiary, they'll scrutinize every purchase to ensure it follows strict SSI rules. If a family member makes a mistake, it could disqualify the loved one from their benefits. This is why many families choose professional special needs planning to act as an agile ally in managing these funds. Professional management reduces the emotional burden on the family while ensuring total compliance with 2026 regulations.
Third-Party Special Needs Trusts: The Legacy Tool for Families
A third-party trust is the most common tool families use to provide a financial safety net for a loved one with a disability. Unlike the first-party options discussed earlier, this trust is funded with assets that never belonged to the beneficiary. Usually, parents, grandparents, or even siblings provide the capital. Among the various types of special needs trusts in Florida, the third-party model is widely considered the gold standard for legacy planning because it avoids the strict Medicaid payback rules.
When the beneficiary passes away, the state of Florida doesn't have a claim on the remaining funds to reimburse Medicaid costs. This allows you to ensure that any leftover assets stay within the family, perhaps passing to the beneficiary's siblings or other relatives. This trust offers immense flexibility; it can hold cash, real estate, or even business interests. For many, it acts as a central hub that integrates seamlessly with a broader revocable trust strategy. It provides a structured way to manage wealth while protecting the beneficiary's eligibility for public assistance.
Stand-Alone vs. Testamentary Third-Party Trusts
Families in West Palm Beach often choose between a stand-alone trust and a testamentary trust. A stand-alone trust is created during your lifetime and is effective immediately. This provides more agility because other relatives can contribute to it through their own estate plans or annual gifts. A testamentary trust, however, is built into your Last Will and Testament and only begins after you pass away. While a testamentary trust might seem simpler to set up initially, it lacks the immediate readiness and multi-contributor flexibility of a stand-alone version.
Coordinating with Life Insurance and Retirement
Life insurance is often the primary "funding engine" for these trusts. By naming the SNT as the beneficiary of a life insurance policy, you ensure a significant influx of capital is available exactly when the loved one needs it most. This is particularly useful when comparing an ABLE account vs. a Special Needs Trust, as the trust can manage much larger sums than the $20,000 annual contribution limit of an ABLE account in 2026.
Planning for retirement assets also requires precision. Under current rules, beneficiaries with disabilities are often "eligible designated beneficiaries," which allows them to stretch out IRA distributions over their lifetime. However, these IRAs must be left to a properly drafted third-party trust to prevent the distributions from counting as income for SSI purposes. You'll need to double-check your beneficiary designations to ensure they align with this legal strategy, as a single clerical error can undo years of careful planning. This level of detail ensures your loved one has a secure financial roadmap that adapts to future needs.
Pooled Trusts and ABLE Accounts: Alternatives for Florida Residents
While individual trusts offer the highest level of customization, they aren't the only way to protect a loved one's future. Pooled trusts represent one of the most accessible types of special needs trusts in Florida, especially for families managing smaller amounts of money or for beneficiaries over age 65. These trusts are established and managed by non-profit organizations that "pool" the resources of many beneficiaries for investment purposes. However, each member maintains a separate sub-account for their specific needs.
Joining a pooled trust is often faster and less expensive than creating a standalone document. Instead of a custom trust deed, you sign a "Joinder Agreement," which is a standardized contract that links your sub-account to the master trust managed by the non-profit. This significantly reduces initial legal fees and provides immediate access to professional management. For many West Palm Beach families, the trade-off is simple: you lose some individual control over investment choices in exchange for lower administrative costs and expert oversight.
The Pros and Cons of Florida Pooled Trusts
The primary advantage of a pooled trust is its inclusivity. Unlike first-party individual trusts, which have a strict age 65 cutoff, pooled trusts can often accept beneficiaries of any age. This makes them an essential tool for seniors who suddenly find themselves with excess assets that threaten their Medicaid eligibility. Professional non-profit trustees also bring deep expertise in SSI and Medicaid rules, reducing the risk of accidental disqualification.
There are downsides to consider, however. Most pooled trusts include a "payback" provision where the non-profit retains a portion of the remaining funds after the beneficiary passes away to support their charitable mission. This means fewer assets may ultimately pass to other family members compared to a third-party trust. In Florida, organizations like The Arc of Florida or the Florida Special Needs Trust Program are common providers that families evaluate when weighing these options.
ABLE Accounts: The "SNT-Lite" Option
As of January 1, 2026, the ABLE Age Adjustment Act has significantly expanded eligibility for tax-advantaged savings. You can now open an ABLE account if the onset of the disability occurred before age 46, a major increase from the previous age 26 limit. In 2026, the annual contribution limit for an ABLE account is $20,000. These accounts are incredibly flexible because they often come with a debit card, allowing the beneficiary to pay for "qualified disability expenses" directly without the oversight of a formal trustee.
Many families don't choose between an ABLE account and an SNT; they use both. A trust can hold large assets like a home or a significant inheritance, while the ABLE account handles smaller, daily expenses. A key feature of Florida’s program, ABLE United, is that the state abolished Medicaid recovery from these accounts in 2019. This means funds left in an ABLE account can often be inherited by family members without state interference. To build a strategy that uses both tools effectively, it's best to consult with an expert in special needs planning who can help you coordinate these limits.
Choosing the Right Trust: A Strategic Framework for 2026
Selecting from the various types of special needs trusts in Florida requires a clear eyed look at your family's specific financial picture. It's not a one size fits all decision. The first question to answer is the source of the funds. If the money already belongs to the beneficiary through a settlement or direct inheritance, a first party trust is your primary tool. If the funds come from your own savings or life insurance, a third party trust offers more flexibility and better legacy options. Matching the legal structure to the money's origin is the only way to ensure total compliance with 2026 Social Security and Medicaid regulations.
Beyond the source of funds, you must consider the long term goal. Some families need a trust for immediate quality of life expenses; others are building a permanent safety net that will last for decades. Administration is another critical pillar. Managing these trusts involves complex tax reporting and strict distribution rules. For 2026, the top federal income tax rate of 37% applies to a trust's undistributed income above approximately $16,000. Proper planning ensures you don't lose a significant portion of the trust to taxes. Working with a probate lawyer in Palm Beach County ensures the trust is integrated into a larger estate strategy, preventing the kind of family litigation that could drain the very funds you're trying to protect.
Selecting a Trustee in Palm Beach County
Choosing a trustee is the most personal part of this process. While a family member knows the beneficiary best, they may feel overwhelmed by the fiduciary duties and reporting requirements. Professional trustees or trust companies offer expertise but can be more expensive. A modern solution for West Palm Beach families is the "Trust Protector" role. This is a third party who has the power to change trustees or modify the trust as laws change. It adds a layer of adaptability that keeps your plan functional even as Florida’s legislative landscape evolves. Local resources in Palm Beach County can provide support for family trustees, but professional oversight is often the safest path for high value trusts.
The Flex Legal, PLLC Advantage: Modern Special Needs Planning
The traditional legal model often feels rigid and slow, but your family needs an agile ally. We've moved beyond the billable hour to offer flat fee special needs packages that provide total price clarity from the start. This allows us to focus on results and adaptability rather than the clock. Our approach at Flex Legal, PLLC is designed for the modern landscape, where speed and transparency are just as important as legal precision. Securing your loved one’s future shouldn't be an intimidating or confusing process. By choosing a partner that understands the 2026 Florida landscape, you're creating a dynamic support system that grows with your family. Scheduling a consultation with Flex Legal, PLLC is the first step toward the peace of mind that comes with a professional, streamlined financial roadmap.
Securing Your Family’s Financial Roadmap
Protecting a loved one’s quality of life requires more than just good intentions; it demands a legal structure that adapts to shifting regulations. By distinguishing between the various types of special needs trusts in Florida, you can ensure that inheritances or settlements provide comfort rather than causing the loss of essential Medicaid or SSI benefits. Whether you choose a legacy focused third party trust or a flexible ABLE account combination, the goal is always to create a clear path forward that respects the beneficiary's independence.
At Flex Legal, PLLC, we act as an agile ally for Palm Beach County families. Led by Jennifer L. Flexer, Esq., our firm specializes in translating complex legal jargon into actionable, modern solutions. We believe in transparency, which is why we offer flat fee estate planning packages that eliminate the stress of unpredictable billable hours. You don't have to navigate these complex rules alone. Secure your loved one’s future with a flat-fee special needs plan from Flex Legal, PLLC. Your family’s peace of mind is within reach, and we're here to help you build a secure, lasting foundation.
Frequently Asked Questions
Can a special needs trust pay for a beneficiary’s housing in Florida?
Yes, a special needs trust can pay for housing, but doing so often triggers a reduction in Supplemental Security Income. In 2026, paying for rent or a mortgage from the trust can reduce an SSI check by up to approximately $351 per month. While this is a trade-off, the benefit of secure housing usually outweighs the reduced monthly payment. It's vital to coordinate these distributions carefully to maintain the beneficiary's overall financial stability.
What is the difference between a First-Party and Third-Party SNT?
The primary difference lies in the source of the money and the rules for what happens when the trust ends. A first-party trust uses the beneficiary's own assets, such as a settlement, and requires a Medicaid payback. A third-party trust is funded by others, like parents, and has no payback requirement. Understanding these types of special needs trusts in Florida is essential for protecting family wealth while securing a loved one's future.
Does a special needs trust affect Medicaid eligibility in Florida?
A properly structured special needs trust does not count against Medicaid eligibility limits. In 2026, the individual asset limit for SSI remains at $2,000, and the Medicaid income cap for long-term care is $2,982. By using the right types of special needs trusts in Florida, the beneficiary remains below these thresholds. This legal shield allows them to receive state-funded healthcare while still benefiting from the private funds held within the trust for their quality of life.
How much does it cost to set up a special needs trust in West Palm Beach?
Costs for special needs planning vary based on the complexity of your family's situation and the specific legal tools required. Instead of traditional hourly billing, many modern firms in West Palm Beach now offer flat-fee estate planning packages. This model provides transparent, fixed-price planning so you know exactly what to expect. You should look for an attorney who provides clear, upfront pricing to ensure your legal strategy remains affordable and predictable from the start.
Can I be the trustee of my child’s special needs trust?
You can certainly serve as the trustee, but the role comes with significant legal and administrative responsibilities. You'll be responsible for meticulous record-keeping, filing tax returns, and ensuring every distribution follows strict Social Security and Medicaid rules. Many parents find these duties overwhelming and choose to work with a professional trustee or an agile legal ally. This partnership ensures the trust remains compliant with Florida law while allowing the family to focus on care.
What happens to the money in a special needs trust when the beneficiary dies?
The outcome depends entirely on whether the trust is a first-party or third-party arrangement. For first-party trusts, the state of Florida must be reimbursed for Medicaid expenses incurred during the beneficiary’s life. Any remaining funds can then pass to heirs. In contrast, third-party trusts do not have a Medicaid payback provision. This allows the remaining assets to pass directly to other family members or charities, making them an excellent tool for long-term family legacy planning.
Is an ABLE account better than a special needs trust?
Neither tool is inherently better; they are designed for different financial needs. An ABLE account is ideal for managing daily expenses and allows for direct beneficiary spending with a debit card. However, it has a $20,000 annual contribution limit in 2026. A special needs trust is better for holding large assets like a home or a significant inheritance. Most families use both tools together to maximize flexibility while maintaining total protection for their government benefits.
Do I need a lawyer to set up a pooled trust in Florida?
While you can technically sign a joinder agreement for a pooled trust without a lawyer, professional guidance is highly recommended. A lawyer ensures that the pooled trust actually fits into your broader estate plan and doesn't conflict with other documents like your Will or Power of Attorney. Because pooled trusts involve giving up some control to a non-profit, having an expert review the agreement helps you understand the long-term implications for your family’s specific needs.


Comments